
TL;DR: The US 10-year yield fell toward 5.19% on Tuesday, extending its retreat from last week’s 5.365% peak, but the Dollar Index has only pulled back modestly from 102.607—leaving Wednesday’s US CPI to decide whether yields and the Dollar finally converge in a deeper correction or diverge once again.
Why This Matters
US Treasury yields extended their retreat on Tuesday, putting fresh pressure on the Dollar ahead of Wednesday’s crucial US CPI release. The 10-year yield fell toward 5.19%, extending its decline from last week’s 5.365% peak, while the Dollar weakened against all seven major counterparts. However, the Treasury market is showing clearer signs of a correction than the Dollar Index, which has only retreated modestly from its recent high of 102.607. The question is whether continued yield declines will eventually force a deeper Dollar pullback, or whether CPI will interrupt the move before that happens.
Treasury Correction Gains Momentum, but Dollar Response Is Muted
The latest decline in yields extends the retreat that began following last week’s Treasury auctions, where solid demand helped support longer-dated bonds. Tuesday’s move was more pronounced in the 10-year than the 2-year yield, suggesting that the decline was not driven solely by a major repricing of near-term Fed expectations. Softer oil prices may have contributed to intraday sentiment, but crude remained above Friday’s closing levels, making energy an incomplete explanation for the broader Treasury recovery.
The Dollar’s response has been more restrained. While the greenback weakened broadly, the Euro’s recovery appears to reflect some stabilization after last week’s sharp losses rather than a clear improvement in European fundamentals. French sovereign-risk concerns have not meaningfully eased. More importantly, the relationship between Treasury yields and the Dollar has been inconsistent. The 10-year yield was already retreating late last week, even as the Dollar Index continued to advance. Tuesday’s simultaneous declines therefore suggest renewed downside pressure on the Dollar, but not yet a decisive change in trend.
ActionForex’s Technical View
US 10-Year Yield Confirms Short-Term Top, Targets 5.081%
Technically, the US 10-year yield’s break below its 4-hour 55 EMA, currently near 5.240%, reinforces the case for a short-term top at 5.365%. The decline is viewed as a correction to the preceding five-wave advance from 4.619%. Bearish MACD momentum also supports the prospect of further downside.
Near-term bias remains on the downside as long as 5.278% resistance holds. The next important target is the 38.2% retracement at 5.081%, where support is expected to emerge. Conversely, a break back above 5.278% would suggest that the correction has already completed and bring a retest of 5.365% back into focus.
Dollar Index Shows Divergence, but No Confirmed Top
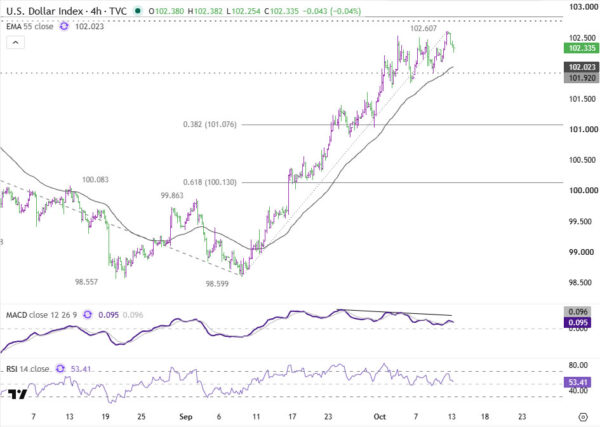
The Dollar Index presents a less decisive technical picture. Although upward momentum has weakened, with bearish divergence appearing on the 4-hour MACD, DXY continues to trade above its rising 55 EMA near 102.023. The underlying short-term uptrend has therefore not yet been broken.
Further declines in Treasury yields could pull DXY toward that moving average and, more importantly, 101.920 support. A firm break below 101.920 would confirm a short-term top at 102.607 and open the way toward the 38.2% retracement of the advance from 98.599 at 101.076. Conversely, a move above 102.607 would indicate that the Dollar’s rally is resuming despite the recent Treasury correction.
CPI Could Decide Whether Yields and Dollar Converge
Wednesday’s US CPI report will provide the next major test. Headline inflation is expected to rise 0.6% month-on-month, largely reflecting higher energy prices, while core inflation is forecast to moderate to 0.2%. The underlying reading is likely to be particularly important for expectations surrounding further Fed tightening.
Softer-than-expected core inflation could reinforce the Treasury recovery, potentially sending the 10-year yield toward 5.081% and increasing pressure on DXY to break 101.920. Conversely, a hotter core reading could revive tightening expectations, interrupt the yield correction and give the Dollar another opportunity to challenge its recent high.
For now, Treasury yields have already entered a more convincing corrective phase, while the Dollar is only showing early signs of losing momentum. Further yield declines could eventually pull DXY lower, but a confirmed Dollar top still requires a break of technical support. Wednesday’s CPI will test whether the two markets finally converge in a deeper correction or diverge once again.
Key Takeaways
- The US 10-year yield fell toward 5.19% on Tuesday, extending its retreat from last week’s 5.365% peak, while DXY has only pulled back modestly from 102.607.
- The relationship between yields and the Dollar has been inconsistent recently—yields were falling late last week even as DXY kept rising, showing the two markets haven’t moved in lockstep.
- Technically, the 10-year yield’s break below its 5.240% EMA points toward 5.081% next, while DXY needs a break below 101.920 to confirm its own short-term top at 102.607.
- Wednesday’s US CPI is the key catalyst: a soft core reading (0.2% or below) could pull both yields and the Dollar lower together, while a hot print could revive Fed tightening bets and halt both corrections.
- Treasury yields have entered a more convincing corrective phase than the Dollar, which is only showing early signs of losing momentum—a gap that CPI could close or widen further.